Thursday, August 6, 2026 / by Vic Markarian
Thinking About Waiting for Lower Mortgage Rates? Read This First.
Thinking About Waiting for Lower Mortgage Rates? Read This First.
Will mortgage rates drop significantly soon? That’s one of the biggest questions homebuyers are asking right now.
If you’ve been waiting to buy a home because you’re expecting mortgage rates to fall dramatically, you’re not alone. Many buyers are hoping rates will eventually return to the unusually low levels we saw during the pandemic.
But there’s an important question to consider:
What if mortgage rates don’t fall as much, or as quickly, as you’re expecting?
Based on the latest forecasts, that’s a real possibility.
The good news is that you don’t necessarily have to choose between buying today at the current rate and waiting indefinitely for rates to fall. There are other strategies that may help improve affordability.
Here’s what today’s homebuyers should know.
1. Mortgage Rates Aren’t Expected To Drop Dramatically
If you’re waiting for mortgage rates to fall below 5%, you’re certainly not alone.
But current forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo don’t point toward a dramatic decline.
Instead, their projections show 30-year fixed mortgage rates generally remaining in the low-to-mid 6% range through at least mid-2027.
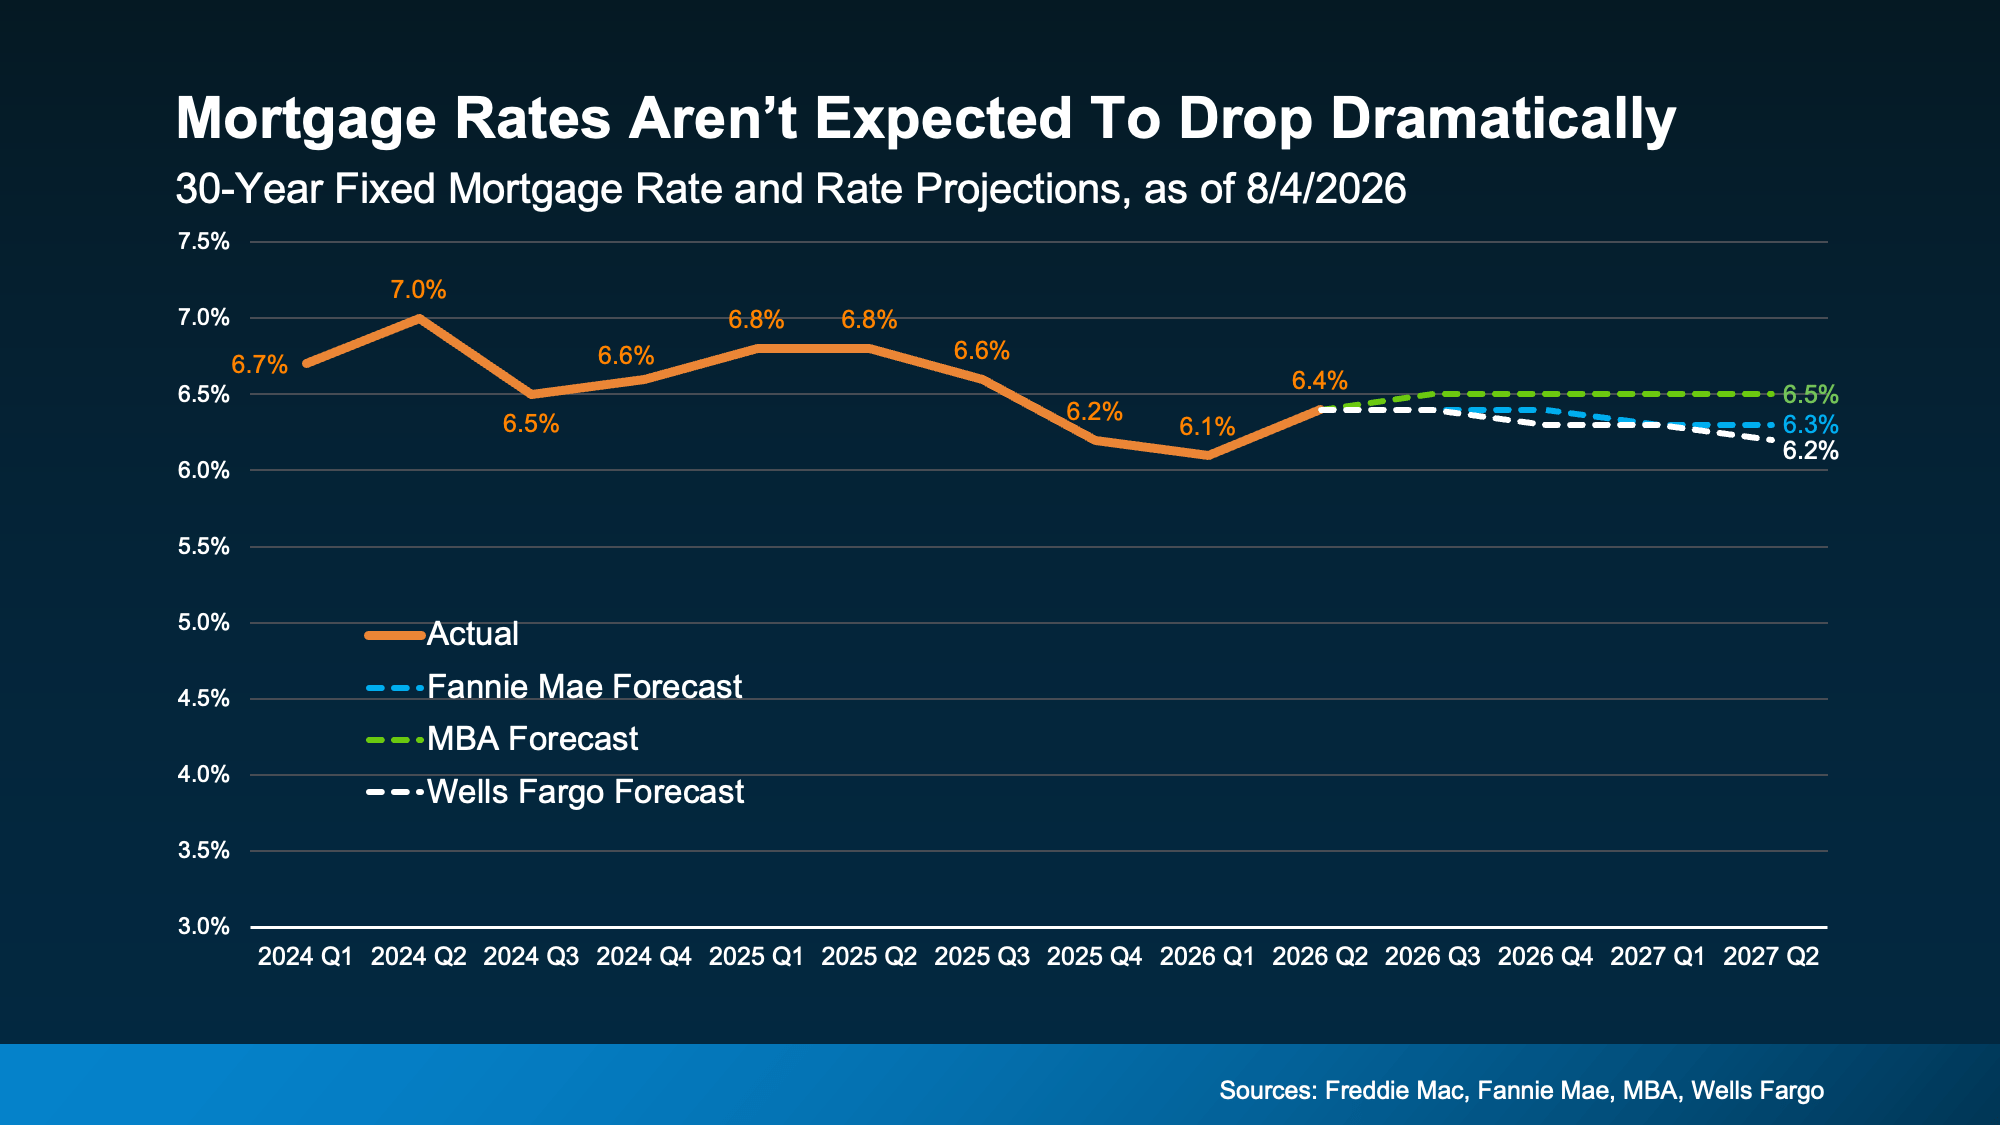
Source: Freddie Mac, Fannie Mae, MBA, Wells Fargo. Forecasts shown as of 8/4/2026.
That doesn’t mean mortgage rates can’t move.
They can.
Mortgage rates are influenced by inflation, economic growth, Treasury yields, Federal Reserve policy, and many other factors. Forecasts can change as those conditions change.
But if your homebuying plan depends on mortgage rates suddenly dropping several percentage points, today’s projections suggest you could be waiting longer than expected.
And waiting has its own variables.
Home prices can change. Inventory can change. Competition can change. And your personal circumstances can change, too.
That’s why it’s important to look at the entire homebuying picture, not just the mortgage rate.
2. Inflation Is Still One Reason Rates May Stay Higher
Why aren’t experts forecasting a major decline in mortgage rates?
One important factor is inflation.
Generally speaking, persistent inflation can make it more difficult for interest rates to fall significantly.
After a period of relative stability, recent data shows inflation has been moving higher again.
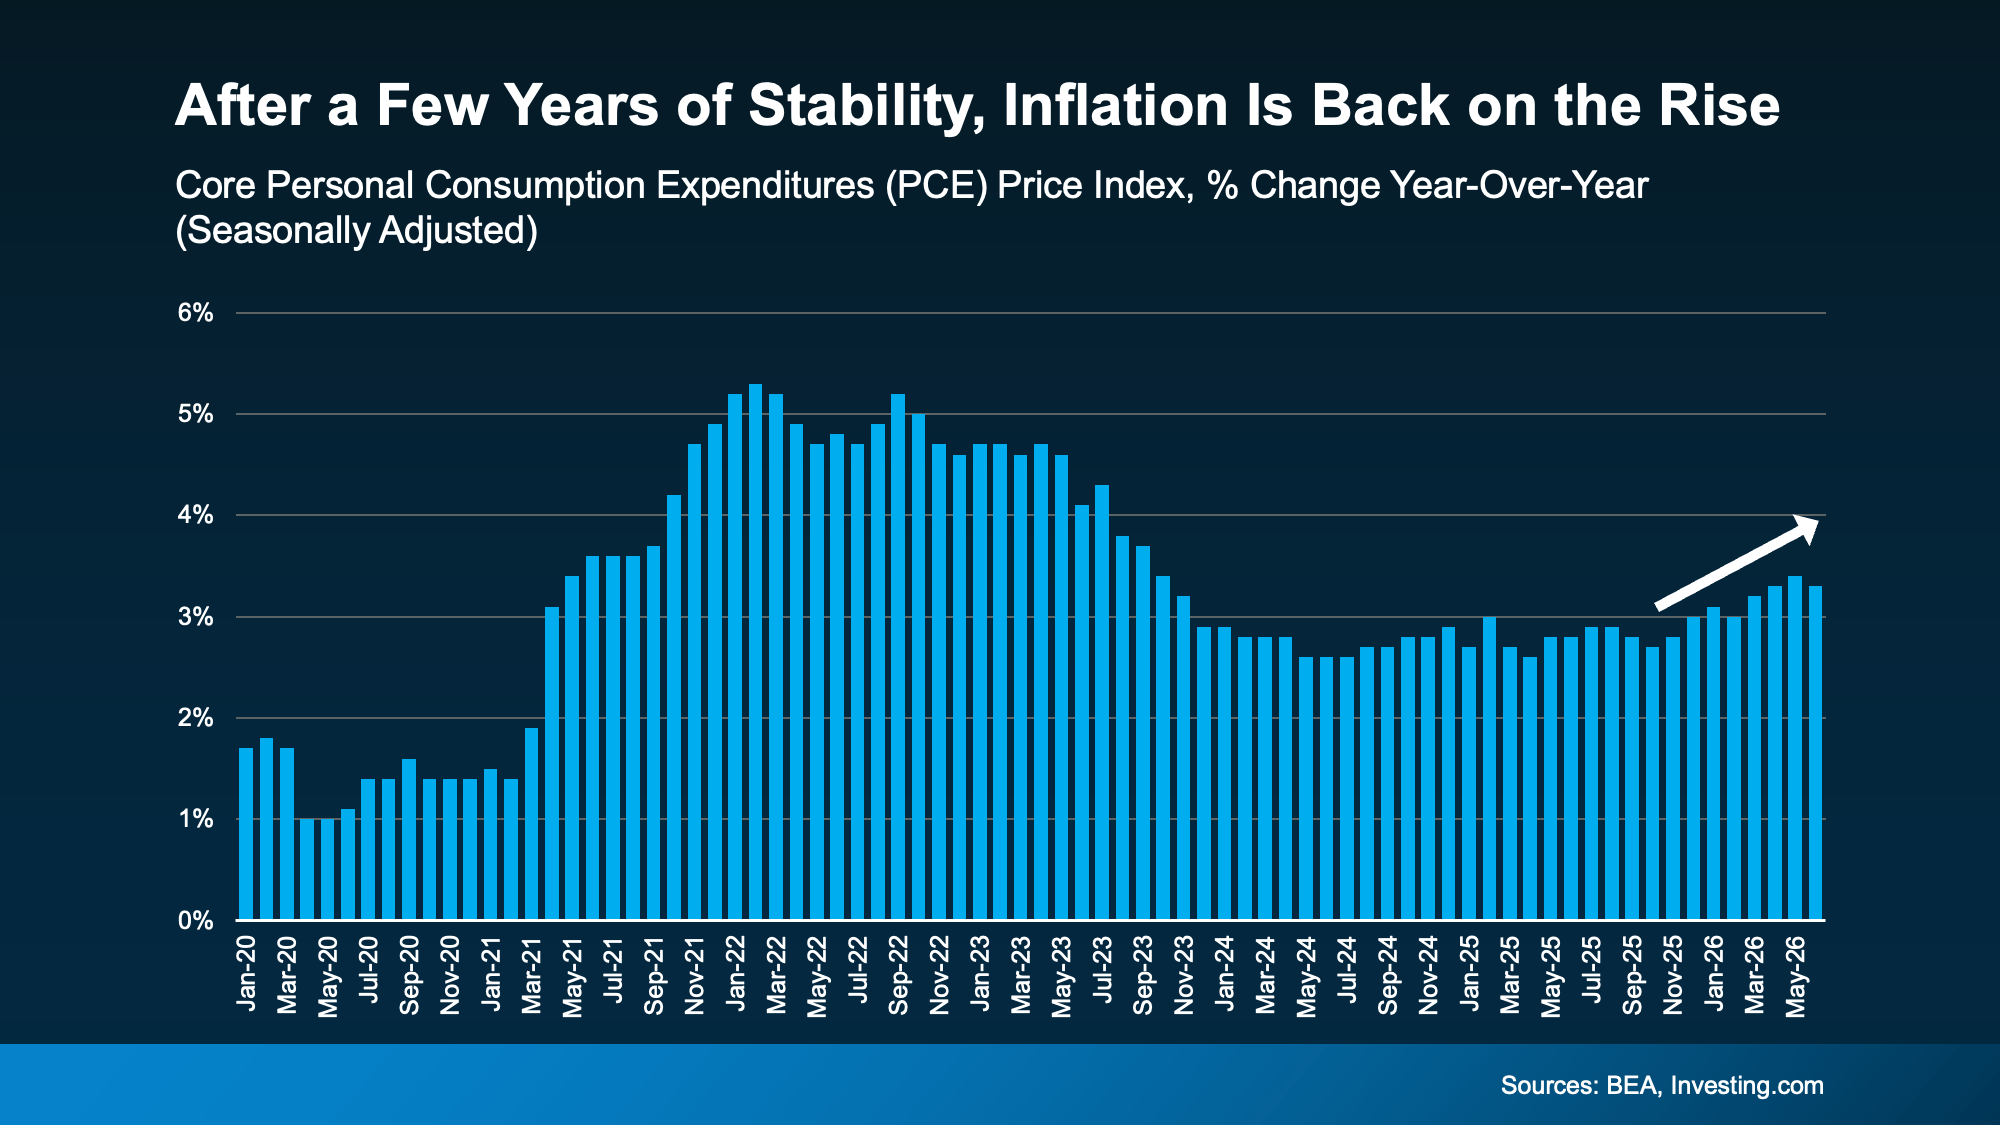
Source: BEA, Investing.com.
That matters because inflation is closely watched when economists and policymakers assess where interest rates could go next.
It doesn’t mean mortgage rates are guaranteed to stay where they are today.
It does mean there are still economic factors working against the kind of dramatic rate decline many buyers are hoping for.
So if you’re waiting specifically for mortgage rates to return to the 3% or 4% range, it’s worth asking yourself whether that’s a realistic short-term assumption, or simply something you hope will happen.
3. Today’s Mortgage Rates May Feel High, But Historically They’re Normal
This may be the biggest mindset shift for today’s homebuyers.
A mortgage rate in the 6% range can feel expensive when you compare it with the 2%–4% rates many homeowners secured during the pandemic.
But historically, today’s rates are not unusual.
Freddie Mac’s long-term data shows mortgage rates have spent much of their history in a considerably higher range than what buyers have experienced over the past decade.
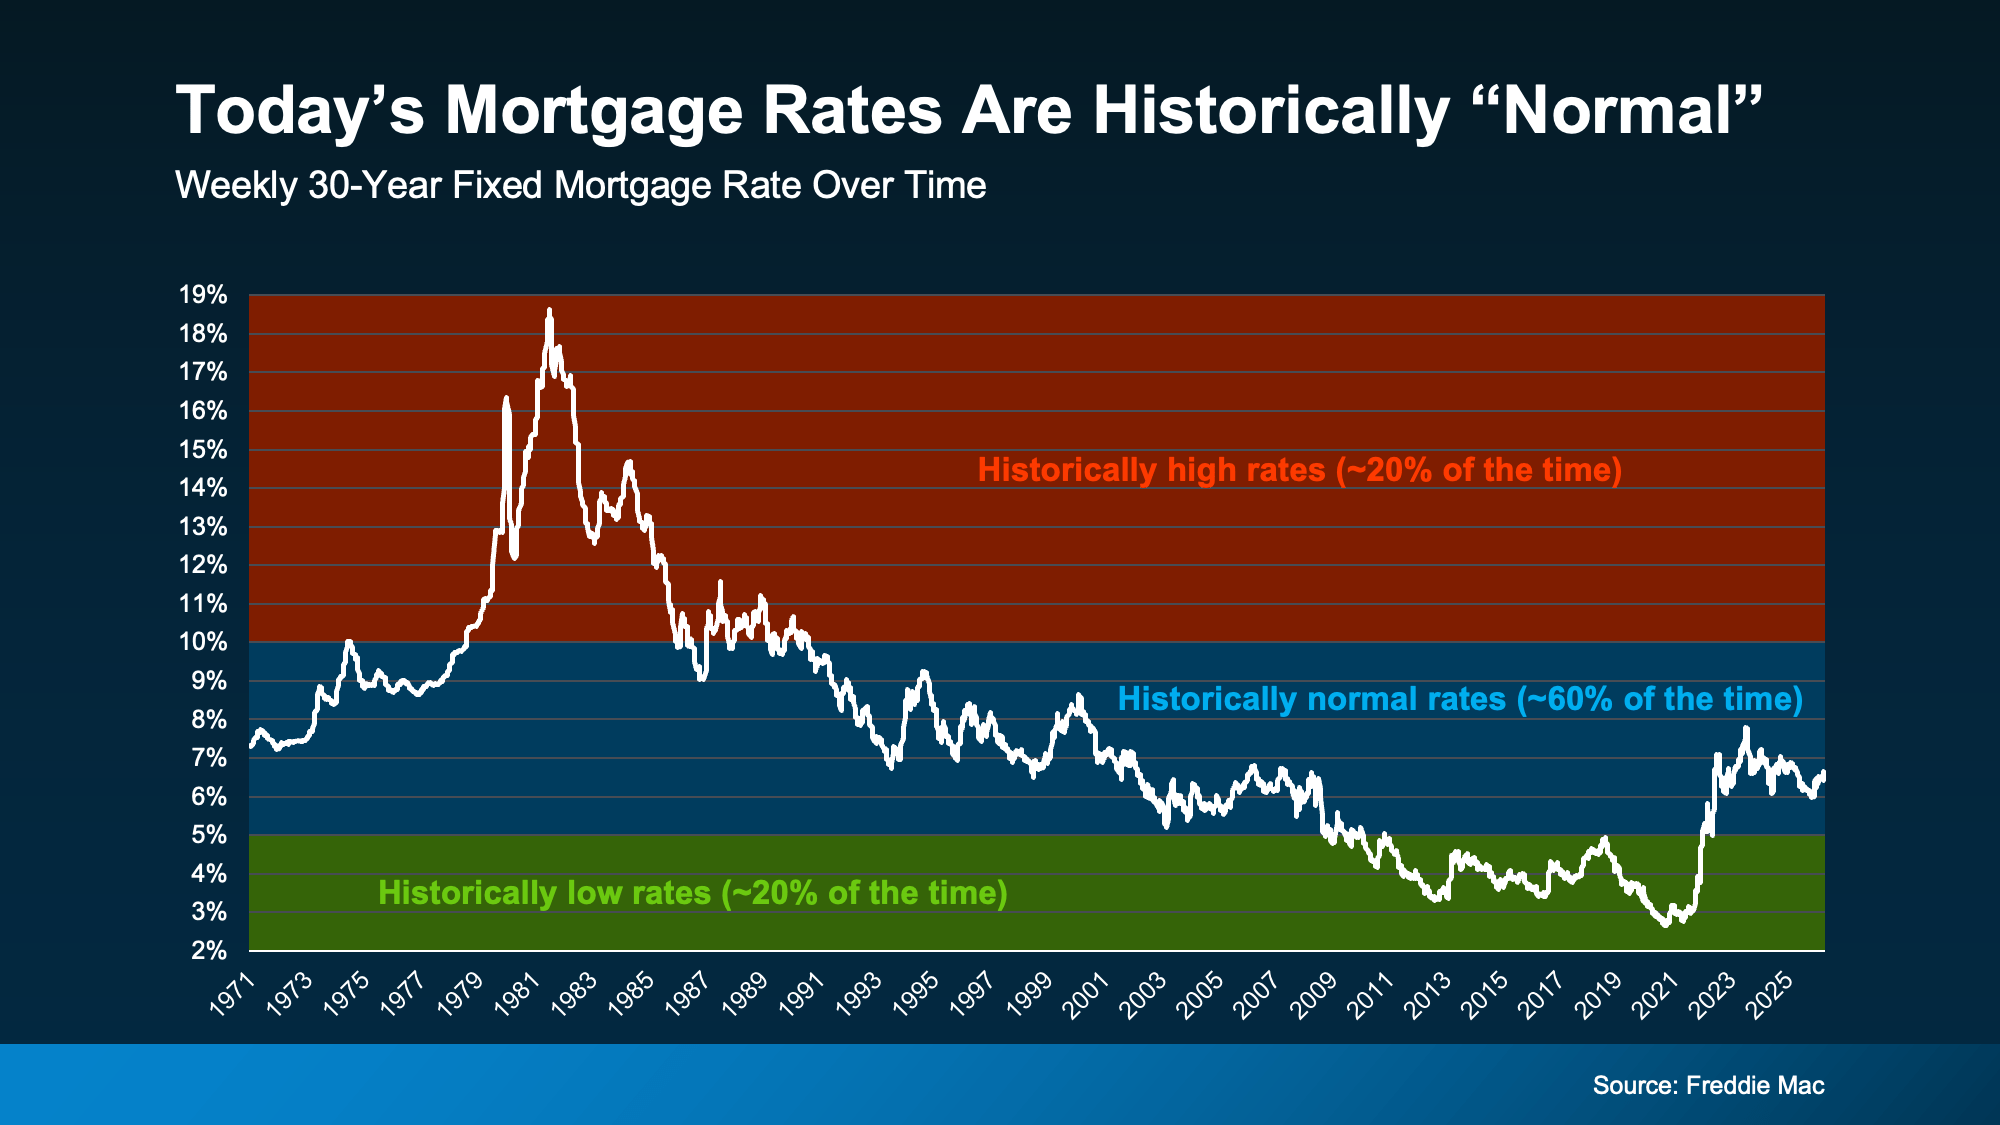
Source: Freddie Mac.
That doesn’t make a 6% mortgage payment feel inexpensive.
Affordability still matters.
But historical context is important because the ultra-low mortgage rates of the pandemic years were the exception, not necessarily the standard buyers should expect to return.
If you’re waiting for those rates to come back before you buy, you could potentially be waiting for something that may not happen anytime soon.
So, Should You Buy Now or Wait?
There’s no universal answer.
Waiting can make sense if you aren’t financially ready, your income or savings need more time to improve, or buying today would put too much pressure on your budget.
But if you’re financially ready to buy and the primary reason you’re waiting is the expectation of dramatically lower mortgage rates, it may be worth exploring your options now.
The goal isn’t to predict the exact bottom of the mortgage-rate market.
It’s to figure out what makes sense for your financial situation and your timeline.
Here are a few strategies worth discussing with your real estate agent and lender.
Look at New Construction
New-home builders sometimes offer incentives to attract buyers.
Depending on the builder and property, those incentives could include:
- Mortgage rate buydowns
- Closing-cost assistance
- Price adjustments
- Upgrades
- Other financing incentives
The key is to compare the overall cost of the home and financing, rather than focusing only on the advertised incentive.
Ask About a Mortgage Rate Buydown
A mortgage rate buydown can potentially reduce your interest rate and monthly payment.
Depending on the structure, the upfront cost may be paid by you, the seller, or a builder.
A lender can help determine whether the numbers make sense based on how long you expect to own the home.
Consider Whether an ARM Fits Your Situation
An adjustable-rate mortgage, or ARM, may offer a lower initial interest rate than a traditional 30-year fixed mortgage.
That doesn’t mean an ARM is automatically better.
Your future rate and payment can change, so it’s important to understand the risks and terms before choosing one.
But if you don’t expect to own the home for a long period, an ARM may be worth discussing with your lender.
Look Into Assumable Mortgages
Some existing mortgages may be assumable.
That can allow a qualified buyer to take over the seller’s existing loan, and potentially the seller’s existing interest rate.
Not every mortgage is assumable, and there are qualification requirements, but it’s another option worth knowing about if affordability is a concern.
The Better Question May Not Be “When Will Rates Fall?”
Instead, ask:
“Will waiting actually put me in a better position?”
That’s a much more useful question.
If mortgage rates fall in the future, refinancing may be an option.
But if you wait a year and rates barely move, you may have spent that year watching home prices, inventory, and your own circumstances change.
On the other hand, buying before you’re financially ready simply because you’re worried rates might rise isn’t necessarily the right move either.
The smartest decision is the one that makes sense for your finances, your lifestyle, and your long-term plans.
What This Means for Los Angeles Homebuyers
For buyers in Los Angeles County, the decision can be even more nuanced.
Affordability, inventory, home prices, and competition can vary significantly between markets such as Glendale, Burbank, La Crescenta, Montrose, La Cañada Flintridge, and surrounding communities.
That means there may not be one answer that applies to every buyer.
Instead of waiting for the perfect mortgage rate, it can be more useful to understand:
- What you can comfortably afford today
- What homes are actually available in your target area
- Whether sellers are offering concessions
- Whether new construction incentives could help
- Whether a rate buydown makes sense
- How much your monthly payment would actually be
- Whether waiting could meaningfully improve your position
That gives you a decision based on your real numbers, rather than a prediction about where mortgage rates might go.
Bottom Line
If you’ve been putting your home search on hold because you’re convinced mortgage rates will be dramatically lower soon, it may be worth taking another look at that strategy.
Current forecasts suggest mortgage rates could remain relatively steady in the low-to-mid 6% range through at least mid-2027, rather than falling dramatically.
That doesn’t mean you need to buy today.
It means waiting isn’t your only option.
New construction incentives, rate buydowns, different loan structures, assumable mortgages, and negotiating the overall terms of a purchase may all help improve affordability.
Your goal shouldn’t be to perfectly predict mortgage rates.
Your goal should be to make the smartest real estate decision for your situation.
If you’re considering buying in Glendale, Burbank, La Crescenta, Montrose, La Cañada Flintridge, or elsewhere in Los Angeles County, understanding what today’s market actually looks like can help you decide whether waiting makes sense, or whether there may already be an opportunity worth exploring.