Thursday, August 20, 2026 / by Vic Markarian
One Number Could Change Everything About Your Next Move
One Number Could Change Everything About Your Next Move
How much equity do you have in your home right now?
If you haven’t checked recently, you may be surprised by the answer.
Not the estimate from an online home valuation tool. Not what your neighbor’s house sold for. And not what you think your home was worth a few years ago.
I mean a current, market-based estimate of what your home could sell for today—and how much equity you may have built along the way.
For many homeowners, that number could change the way they think about their next move.
Your Home May Have Built More Equity Than You Realize
Home prices have increased significantly over the past several years. At the same time, homeowners have continued building equity through a combination of home appreciation and paying down their mortgage.
According to Cotality, the typical U.S. homeowner with a mortgage had about $310,500 in equity as of Q2 2026.
That’s a significant amount of wealth tied to homeownership.
And the national average only tells part of the story.
Equity varies considerably from state to state, and local market conditions can be very different from national trends.
Here’s how average homeowner equity compares across the country:
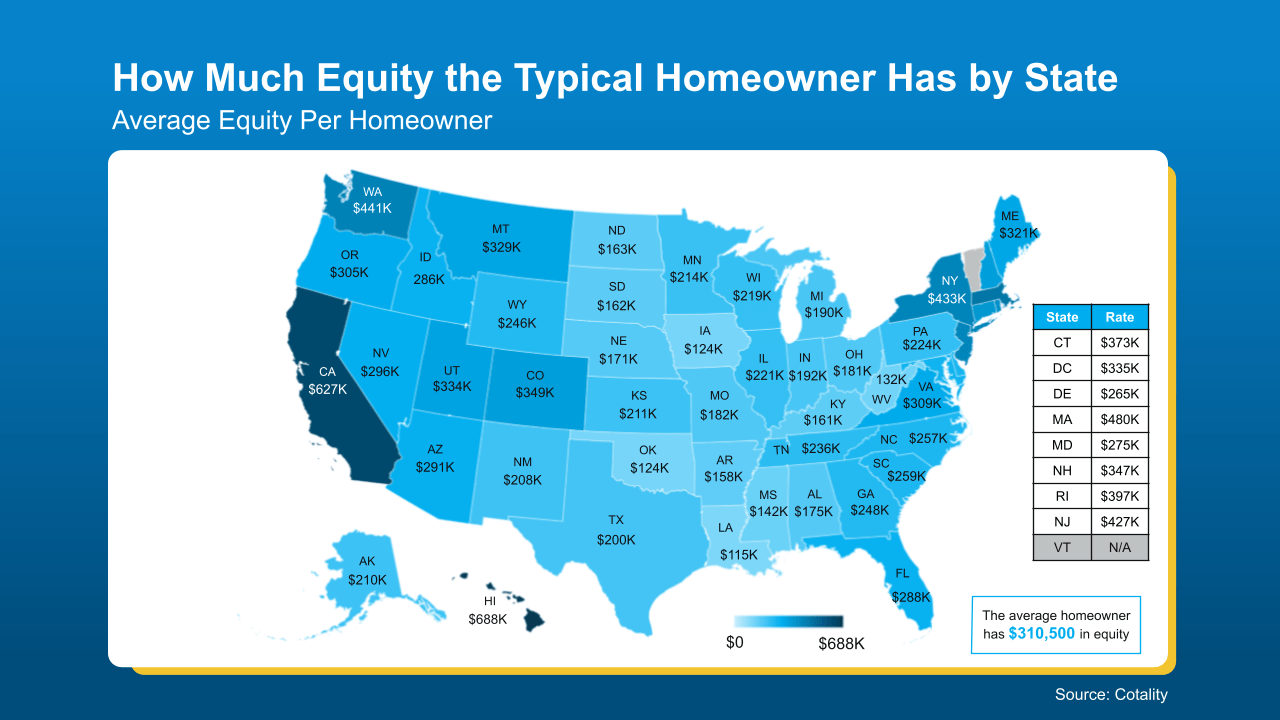
The important question isn't simply what the average homeowner has.
The question is: How much equity have you built in your home?
Because that number could be one of the most important pieces of information when deciding what comes next.
Your Equity Could Change the Math on Your Next Move
One reason homeowners are hesitant to move today is understandable.
Mortgage rates aren't what they were a few years ago. Home prices are higher in many markets. And if you currently have a very low mortgage rate, giving that up can feel like a major financial sacrifice.
But there’s another side of the equation that’s easy to overlook:
Your equity.
If you've owned your home for several years, you may not be starting from scratch when you consider your next purchase.
You may have built a substantial amount of equity that can potentially be used toward your next move.
That can change the numbers considerably.
What Can You Actually Do With Your Home Equity?
Your equity isn't just a number on paper.
Depending on your financial situation, your goals, and the amount of equity you've built, it may give you several options.
1. Put More Money Down on Your Next Home
Selling your current home and using a portion of your equity toward your next purchase could allow you to make a larger down payment.
That means borrowing less money.
And with today's mortgage rates, reducing the amount you need to borrow can make a meaningful difference in your monthly payment.
It can also potentially give you more flexibility when choosing your next home.
2. Potentially Buy Your Next Home With Cash
This may sound surprising, but some homeowners have accumulated enough equity to make an all-cash purchase possible.
According to the National Association of Realtors, 26% of repeat buyers paid cash for their homes in July.
Of course, that doesn't mean every homeowner can, or should, buy their next home with cash.
But it does show how powerful accumulated home equity can become over time.
3. Renovate Instead of Moving
Moving isn't always the answer.
Maybe you love your neighborhood.
Maybe your kids are established in the schools.
Maybe you've built relationships with your neighbors and don't want to start over.
But perhaps your kitchen is outdated, you need another bedroom, or your current floor plan no longer works for your lifestyle.
In that situation, your equity may potentially give you another option: improving the home you already own.
Instead of asking, "Where should I move?"
You might first ask:
"What would it cost to make the home I already love work better for me?"
What About Homeowners in Los Angeles?
This is where national numbers become less useful.
Real estate is local.
The amount of equity you've built depends on when you purchased, what you paid, how much you still owe, and how your specific neighborhood has performed.
A homeowner in Glendale, Burbank, La Crescenta, La Cañada Flintridge, or another Los Angeles-area community can have a very different equity position from the national average.
And even two homes on the same street can have different values depending on condition, improvements, lot size, layout, and other factors.
That's why an online estimate shouldn't be the final word.
Your equity starts with knowing what your home is actually worth today.
The Number You Should Know Before Making a Move
If you're considering selling, buying, downsizing, moving up, or even renovating, there are really three numbers worth understanding:
1. What could your home sell for today?
2. How much do you still owe on your mortgage and other liens?
3. How much equity could potentially be available after selling costs?
Once you understand those numbers, the conversation becomes much more practical.
Instead of simply asking:
"Can I afford to move?"
You can start asking better questions:
- What price range could I realistically move into?
- How much would my next mortgage be?
- Could I make a larger down payment?
- Would downsizing allow me to unlock significant equity?
- Would staying and renovating make more financial sense?
- What would my estimated net proceeds look like if I sold?
- How would different purchase prices affect my monthly payment?
That's where a professional equity analysis can be extremely useful.
Don't Guess. Know Your Number.
Your home may be your largest financial asset.
Yet many homeowners have no idea how much equity they've actually accumulated.
And that's a number worth knowing, even if you're not planning to move anytime soon.
A Professional Home Equity Assessment can give you a more realistic picture of your home's potential market value, your estimated equity, and what that equity could mean for your future options.
You may discover that moving isn't realistic right now.
You may discover that staying put makes more sense.
Or you may discover that you have considerably more flexibility than you thought.
The point isn't to convince you to sell.
It's to make sure you know what you have before deciding what to do next.
Bottom Line
The real question isn't simply, "What is my house worth?"
It's:
"How much equity have I built, and what could that equity allow me to do?"
If you haven't had your home value and equity reviewed recently, now is a good time to find out.
Because once you know the number, you can make your next decision based on your actual financial position... not assumptions.